
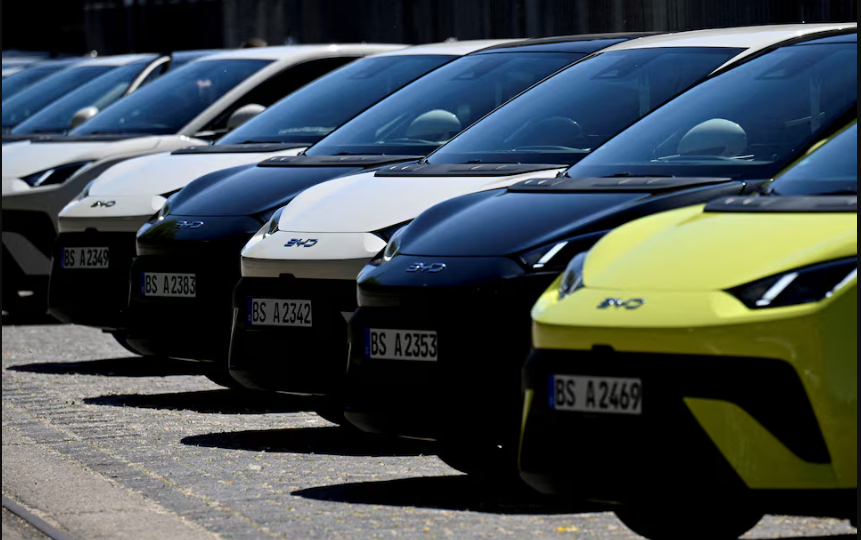

Despite a downturn in overall European new car sales, Chinese automakers are surging ahead nearly doubling their market share in the first half of 2025, industry data reveals.
European Market Contracts, Chinese Brands Thrive
- According to JATO Dynamics, European car registrations fell 4.4% in June, totaling around 1.25 million units, yet Chinese-branded vehicles continued gaining traction.
- In H1 2025, Chinese automakers achieved a 5.1% market share, up from approximately 2.6% in early 2024, coming just shy of Mercedes-Benz’s 5.2%.
Rapid Growth Drivers: Brands & Powertrains
- BYD led the charge, delivering 70,500 vehicles, a 311% year-over-year increase. Other standout brands include Jaecoo, Omoda, Leapmotor, and Xpeng.
- Explosion in hybrids and plug-in hybrids: Chinese PHEV sales surged over 368%, and HEVs rose 100%, addressing EU tariffs levied on pure electric vehicles (BEVs).
May Snapshot: Market Share Soars
- In May 2025 alone, Chinese-branded registrations jumped to 65,808 units, up 111% y/y, amounting to 5.9% of the total European market.
- MG sold 29,400 units up 30%, overtaking Fiat in year-to-date volumes, while BYD’s registrations surged 397%, touching Tesla-level performance for the month.
Tesla and Legacy Automakers Feel the Pressure
- Tesla’s European sales tumbled dramatically dropping 37–45% across early 2025, with market share falling to as low as 0.7–1.6%, depending on the period. BYD outsold Tesla in BEV segment for the first time in April.
- Stellantis also saw its market share decline to 15.3% (down from 16.7%), underscoring mounting pressure from fast-growing Chinese brands.
Strategy & Industry Response
- Chinese automakers are riding momentum built on strong product pricing, expanding hybrids to bypass EU BEV tariffs, and deploying superior battery and software tech.
- Industry insiders note Europe is transitioning from teaching China vehicle tech to being influenced by Chinese innovation. European incumbents like VW, BMW, and Mercedes are now forming joint ventures or investing into China-linked initiatives.
Regional Variations: Where Chinese Brands Are Strongest
- In Norway, Chinese brands hold the highest share (~9%), benefiting from high BEV adoption. In markets like Spain, Turkey, and the UK, Chinese firms gained over 7% share, aided by local production, hybrid offerings, and competitive pricing.
- Premium vehicle segments in countries like Switzerland and Sweden pose more resistance, but Chinese players continue expanding into these markets with new luxury or mid-premium models.
What Comes Next?
- With EU imposing tariffs up to 45% on Chinese BEVs, the shift toward hybrids and plug-in hybrids is a strategic workaround that Chinese automakers exploit successfully.
- As registrations continue to climb, the EU–China trade dynamic is likely to attract increasing scrutiny and may provoke stronger protectionist policies especially as Chinese firms edge closer to matching or surpassing traditional European leaders.
- Consumer appetite for tech-rich, affordable EVs remains strong. Whether established European brands can respond nimbly to this disruptive wave will shape the future of the continent’s auto industry.
Chinese automakers are no longer fringe competitors in Europe they’re fast becoming mainstream. With surging registrations, hybrid-first strategies, and aggressive pricing, brands like BYD, MG, and Leapmotor are redefining competition while pushing legacy automakers to adapt or risk being overshadowed.